Marketing Strategy · Positioning · Focus
Why Good Marketing Strategy Usually Means Saying No
Most businesses do not suffer from a shortage of opportunities. They suffer from too many of them. Strategy becomes useful when it helps you reject attractive things that do not fit — products, customers, channels, partnerships and even growth.
Saying yes is easy to make look strategic.
A new product creates a launch plan. A new audience creates a campaign. A new advertising opportunity creates a media proposal. A new retailer creates a sales forecast. A new channel gives everyone something fresh to put into a presentation.
Saying no creates considerably less PowerPoint.
But it may be the more important decision.
Michael Porter made the point particularly clearly in his 1996 Harvard Business Review article What Is Strategy?: “The essence of strategy is choosing what not to do.” His argument was not that businesses should become stubborn or stop experimenting. It was that a distinctive position requires trade-offs. If you attempt to serve every need in every way, your activities eventually pull in different directions.
Strategy is not deciding what you could do. It is deciding what you will not do, even when the opportunity looks attractive.
I think that is one of the hardest parts of marketing.
Most opportunities do not arrive labelled Bad Idea.
They arrive looking quite good.
The Most Dangerous Opportunities Are Often the Plausible Ones
I receive an absurd number of opportunities.
On some days I can get around 30 LinkedIn messages. In a busy week, 50 or more inbox approaches is perfectly plausible, alongside another stream of emails offering advertising, partnerships, media placements, events, directories, sponsorships and things that apparently need to be decided by Friday.
Some of them are obviously irrelevant.
The difficult ones are the opportunities that sound reasonable.
A publication offers a heavily discounted first campaign. A platform gives you an introductory rate. A salesperson has a package that reaches roughly the right audience. The cost is low enough that saying yes feels easier than spending half an hour deciding whether the answer should be no.
Then, if the first activity happens, you have created a second decision.
The introductory offer becomes a conversation about the full rate. The one-off test becomes an expectation of repeat spend. Declining later can become more awkward than declining at the start.
That does not mean marketers should never test anything. Testing matters.
It means “we can afford to try it” is not the same as “this deserves our attention”.
Time, attention and organisational energy are strategic resources too.
Every yes quietly contains several noes.
A campaign takes budget from another campaign. A new SKU takes production capacity from another SKU. A new audience takes creative attention away from the audience you already chose to serve.
At Paleo Ridge, “Raw Is Best” Has to Mean Something
The clearest example from my own work is raw dog food.
Over time, stakeholders have suggested opportunities that make sense if you look at them only as market opportunities: vegan dog food, cooked food and other formats outside raw feeding.
I have consistently thought those would weaken the brand.
Paleo Ridge says raw is the best way to feed a dog. I genuinely believe that. If the same brand then starts selling cooked food or a vegan range because there is demand for it, the question becomes obvious:
If raw is best, why are you selling me something you believe is second best?
There may be perfectly good businesses in those categories. That is not the point.
The point is that an opportunity can be commercially interesting and strategically wrong for a particular brand.
I have seen other companies — which I will leave unnamed — move into almost any adjacent space that becomes available. Eventually the brand starts to feel less like a conviction and more like a container for whatever management thinks it can sell this year.
That damages authenticity.
It also waters down positioning, because positioning depends partly on knowing what a brand is not.
Ryanair Does Not Secretly Want to Be British Airways
Ryanair is an unusually visible example of strategic trade-offs because customers experience them directly.
Its 2026 annual report still describes the strategy around low fares, cost containment and operating efficiency. That sounds obvious because Ryanair has repeated it for so long.
But consistency is the point.
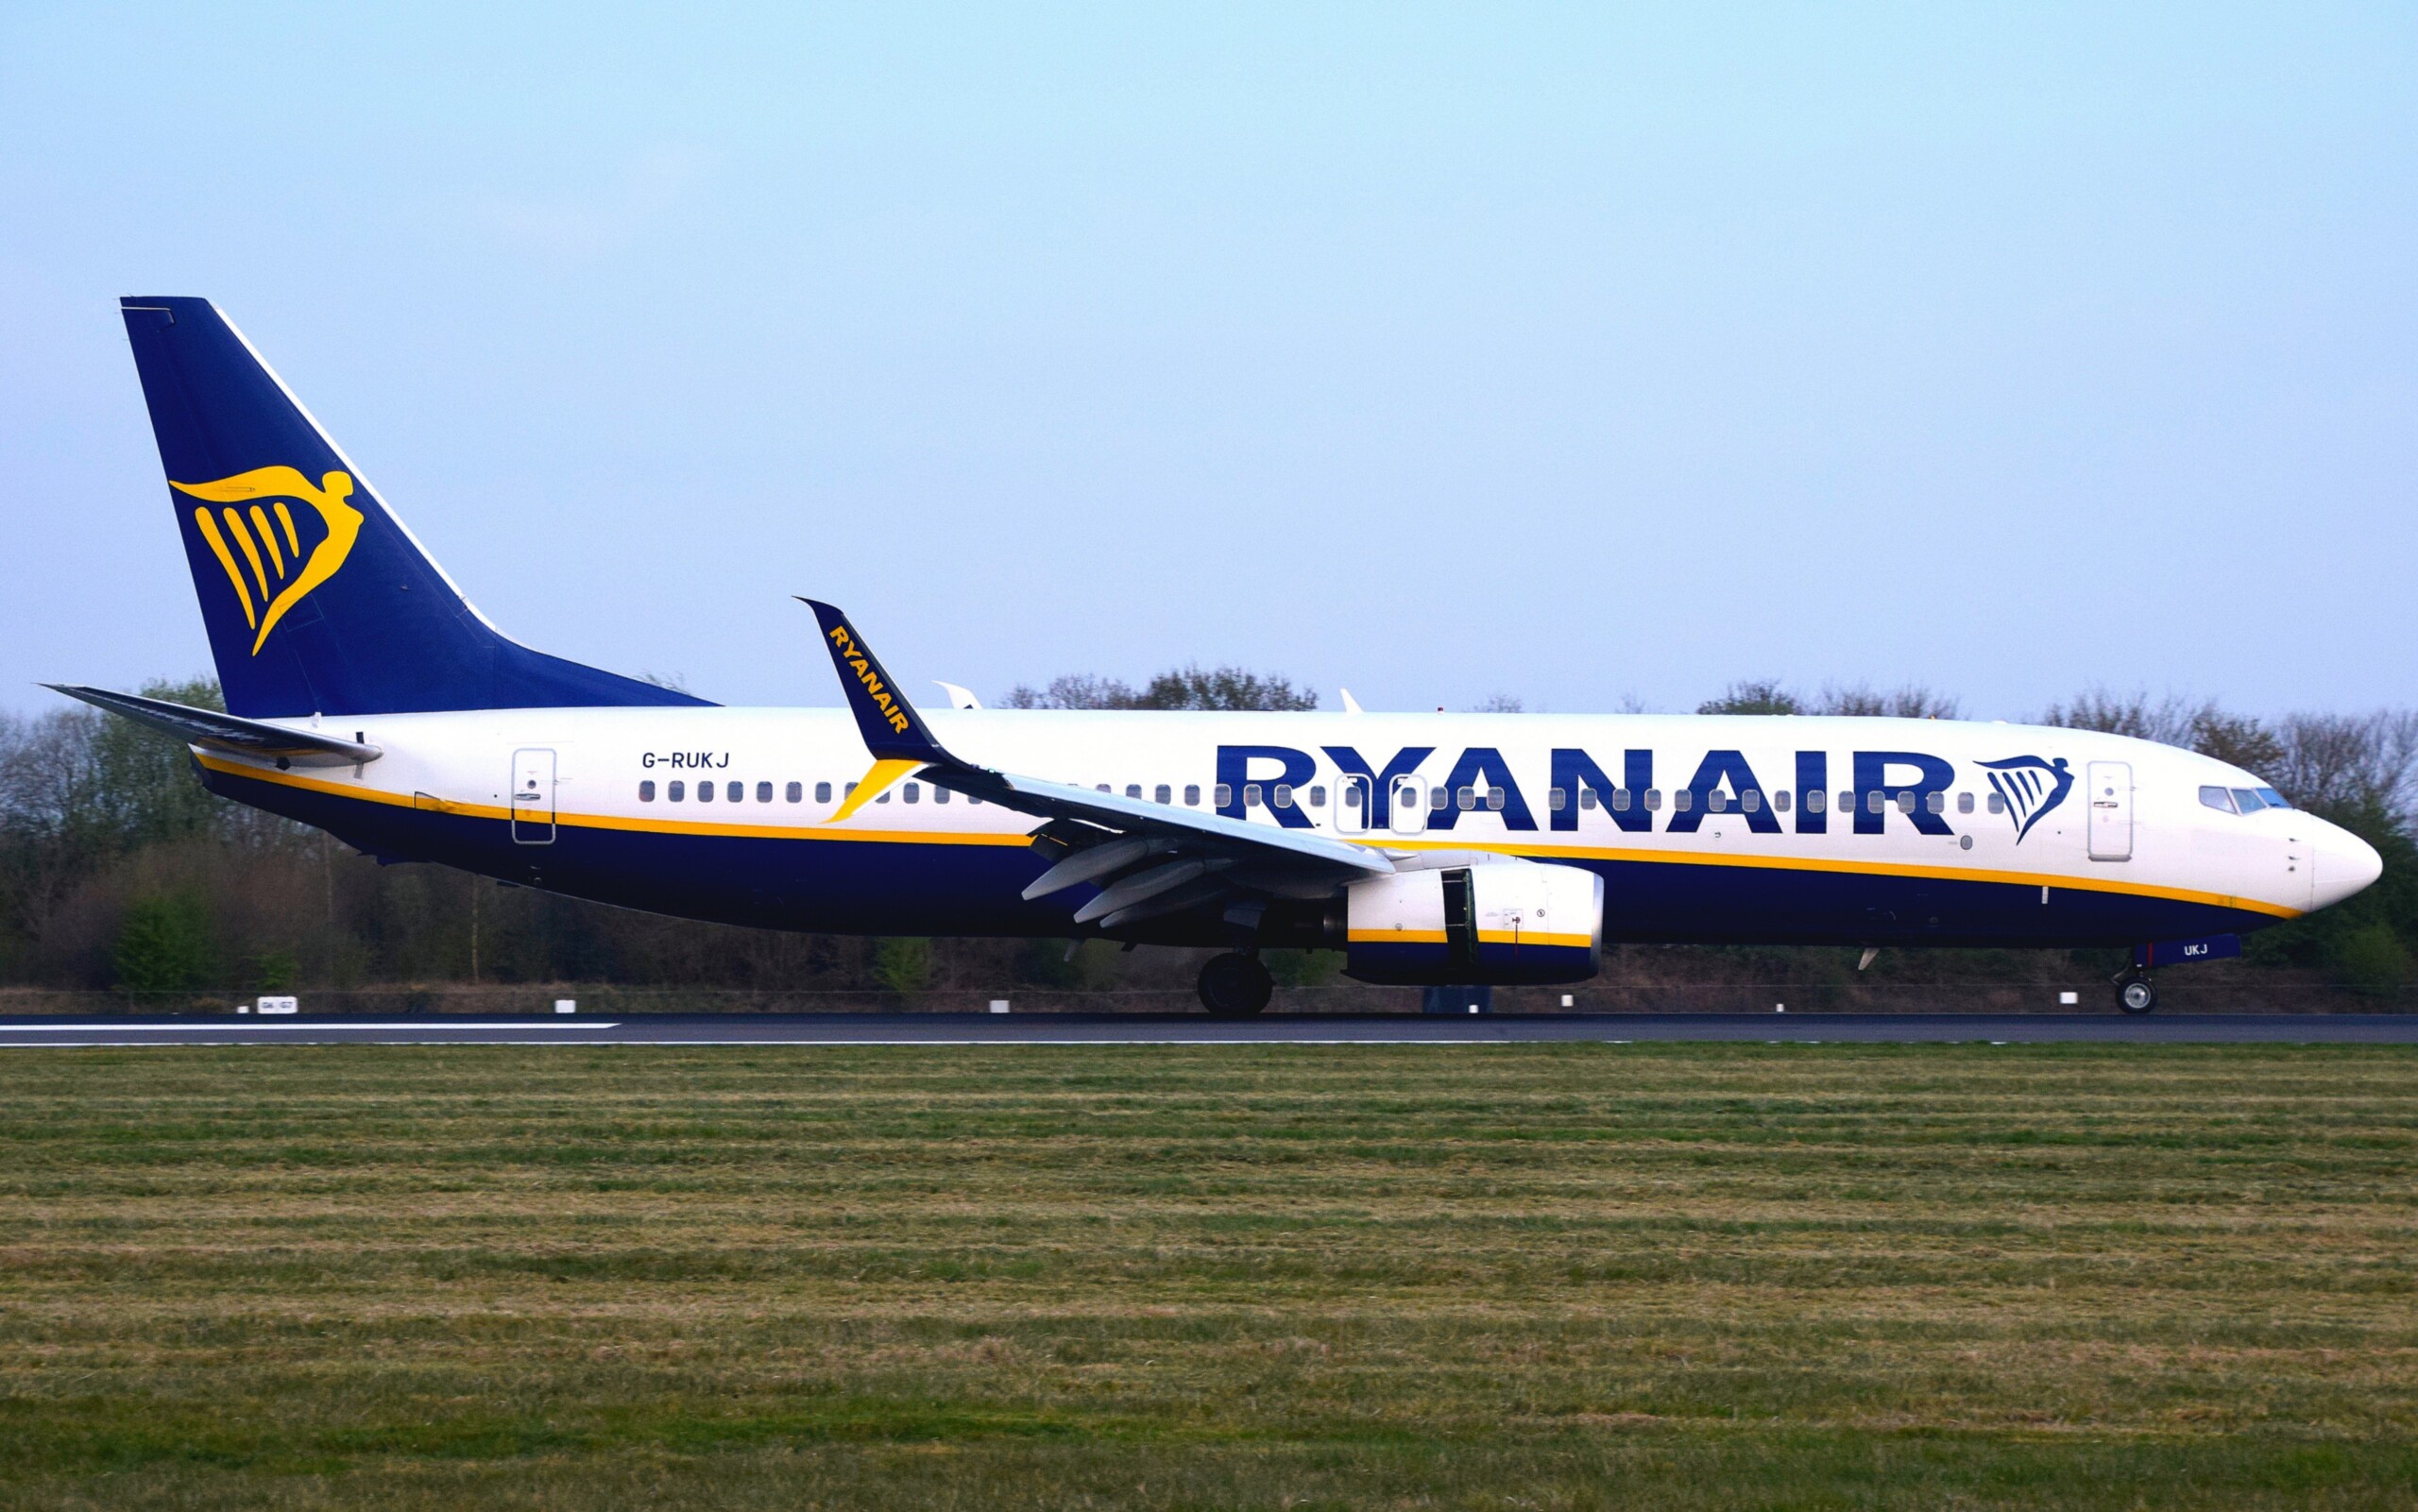
The airline can improve customer service and reliability without trying to become a traditional premium carrier. Those are different things.
A strategy of low fares does not require bad execution. It does require resisting features, complexity and costs that undermine the underlying model.
If Ryanair attempted to add every premium service competitors offer, the proposition would not simply become “better Ryanair”. The economics that make Ryanair possible would begin to change.
That is the part businesses often miss.
Trade-offs are not an unfortunate side effect of strategy.
They are evidence that a strategy exists.
Aldi Wins Partly Because It Does Not Try to Be Every Supermarket
Aldi makes a similar point in retail.
Its UK proposition is built around everyday low prices, own brands and a deliberately recognisable way of shopping. It does not need to reproduce every aspect of a traditional supermarket in order to compete with one.
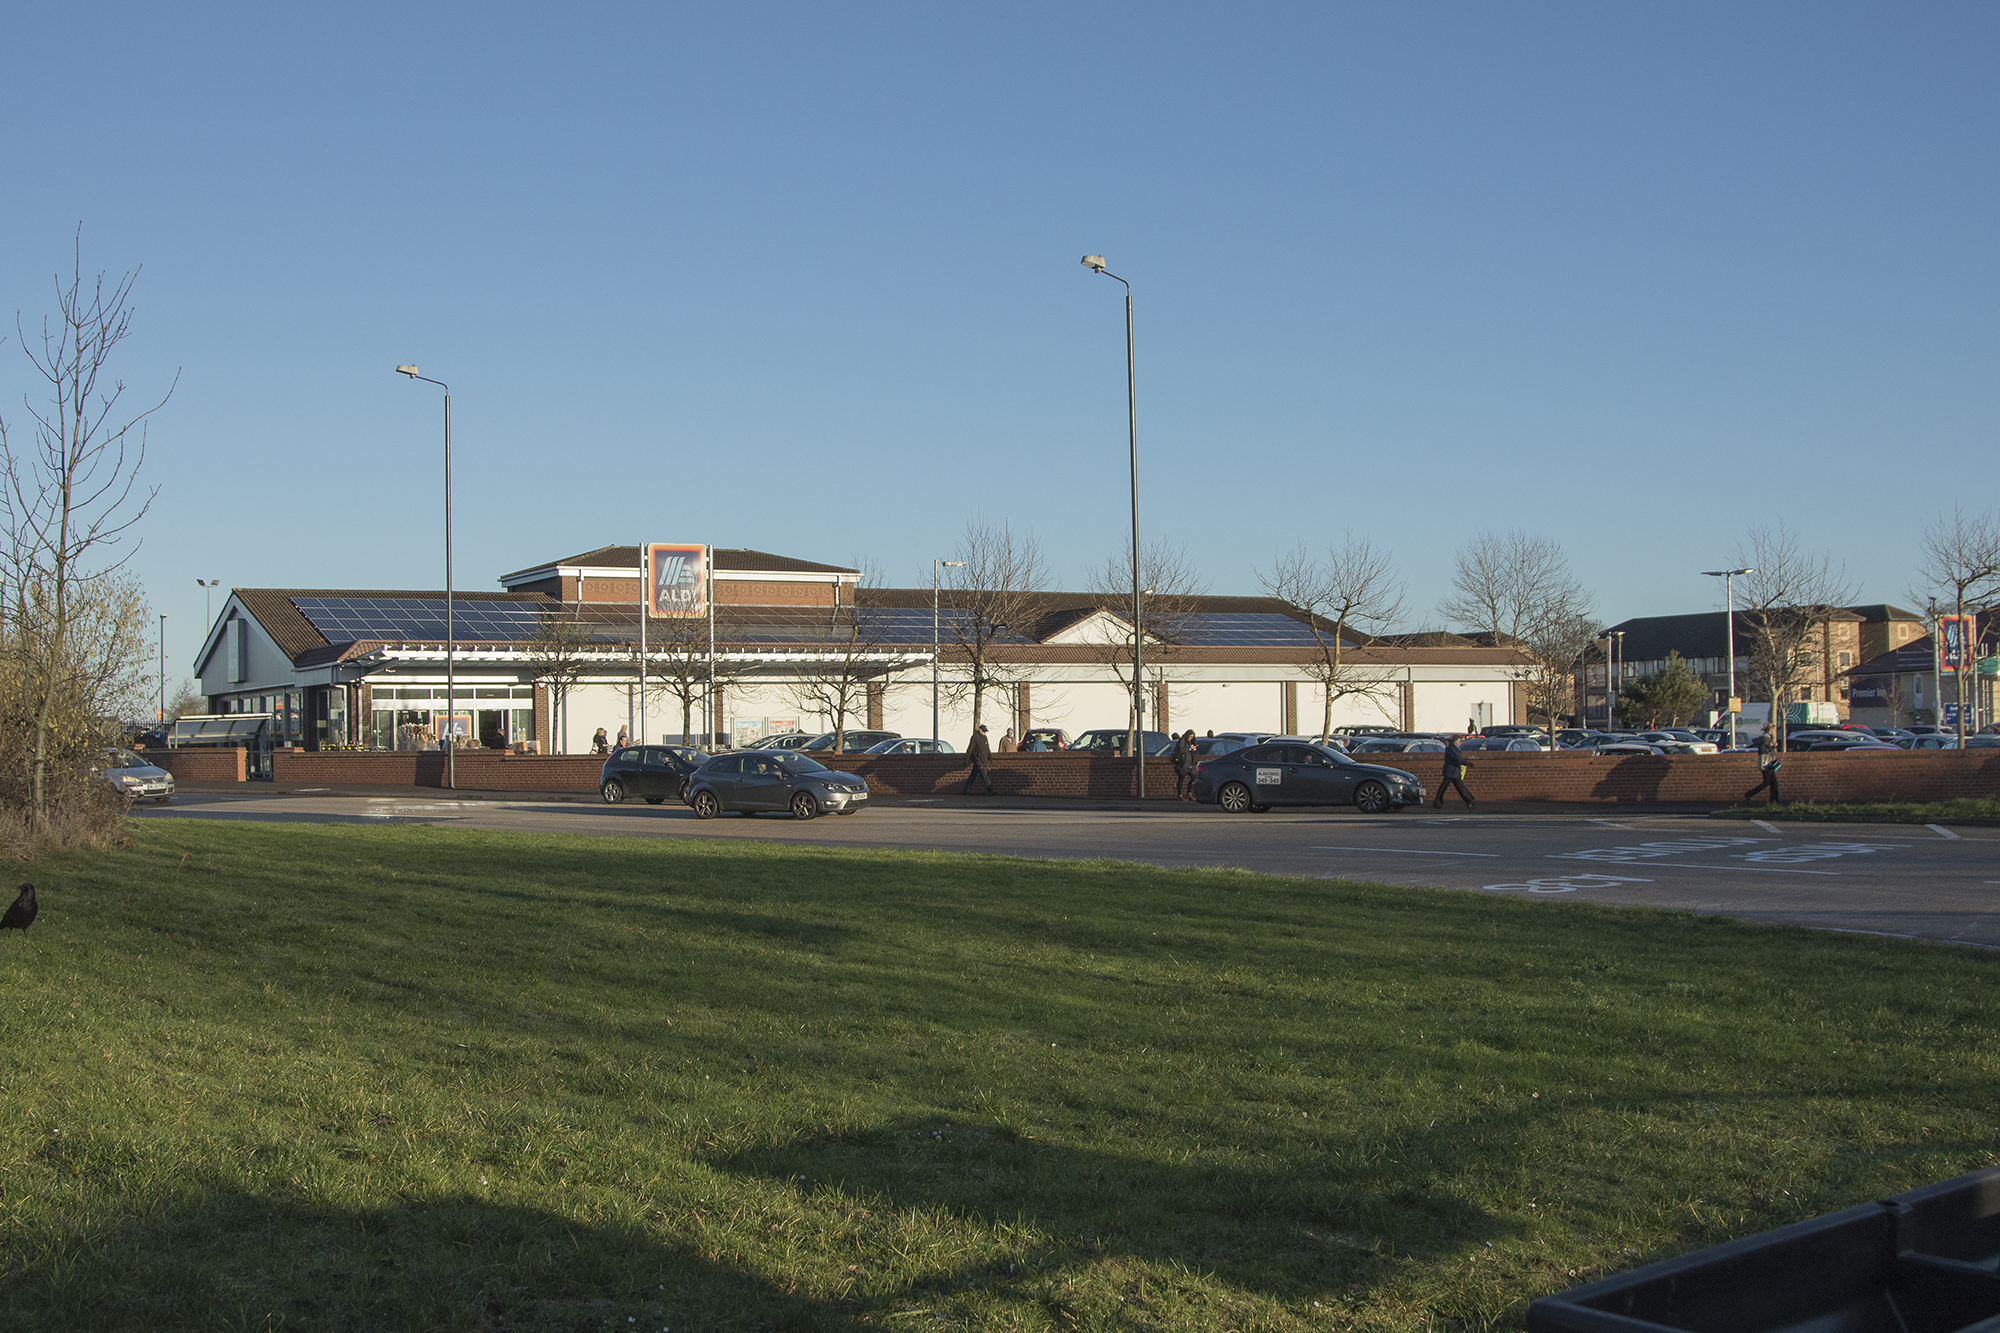
This is a useful distinction because marketers sometimes treat customer requests as instructions.
If one customer wants more choice, another wants more services and a third wants a different experience, it can feel customer-centric to keep adding.
But a proposition is not a referendum in which every request must eventually become policy.
Aldi can listen to customers without deciding it must become Sainsbury’s.
Ryanair can improve without deciding it must become Emirates.
Focus does not mean refusing to evolve.
It means evolving without losing the reason the business is distinctive.
Growth and Breadth Are Not the Same Thing
This is particularly obvious in manufacturing.
People naturally associate growth with more: more products, more variants, more audiences, more channels.
Operationally, that can be exactly the wrong kind of growth.
If you manufacture something, selling more of one successful product can be far easier and more profitable than selling the same total volume across ten products.
Every additional SKU can bring another forecast, another stockholding decision, another ingredient or component, another packaging configuration, another production changeover and another opportunity to run out of the wrong thing at the wrong time.
Revenue may go up while complexity goes up faster.
This is why breadth can flatter a business.
The range looks bigger. The total addressable audience looks bigger. The presentation has more boxes in it.
The factory has to live with the consequences.
Growth or Complexity?
Scale what already works
Higher volume can improve purchasing, production efficiency, brand familiarity and operational confidence.
Add choice carefully
Each extension creates demand for forecasting, inventory, production capacity, packaging and communication.
Ask whether they value the same thing
Growth is healthier when new customers are attracted by the existing proposition rather than requiring it to be rewritten.
Do not mistake availability for strategy
A channel is useful when it reaches the right customer in the right context, not simply because it exists.
Ferrari Is Willing to Leave Sales on the Table
Ferrari is useful because it makes the sacrifice explicit.
Its 2025 annual report says controlled production volumes are used to preserve exclusivity and scarcity. The company even identifies the obvious risk: limiting volume can limit potential sales and profit.
That is strategy in unusually pure form.
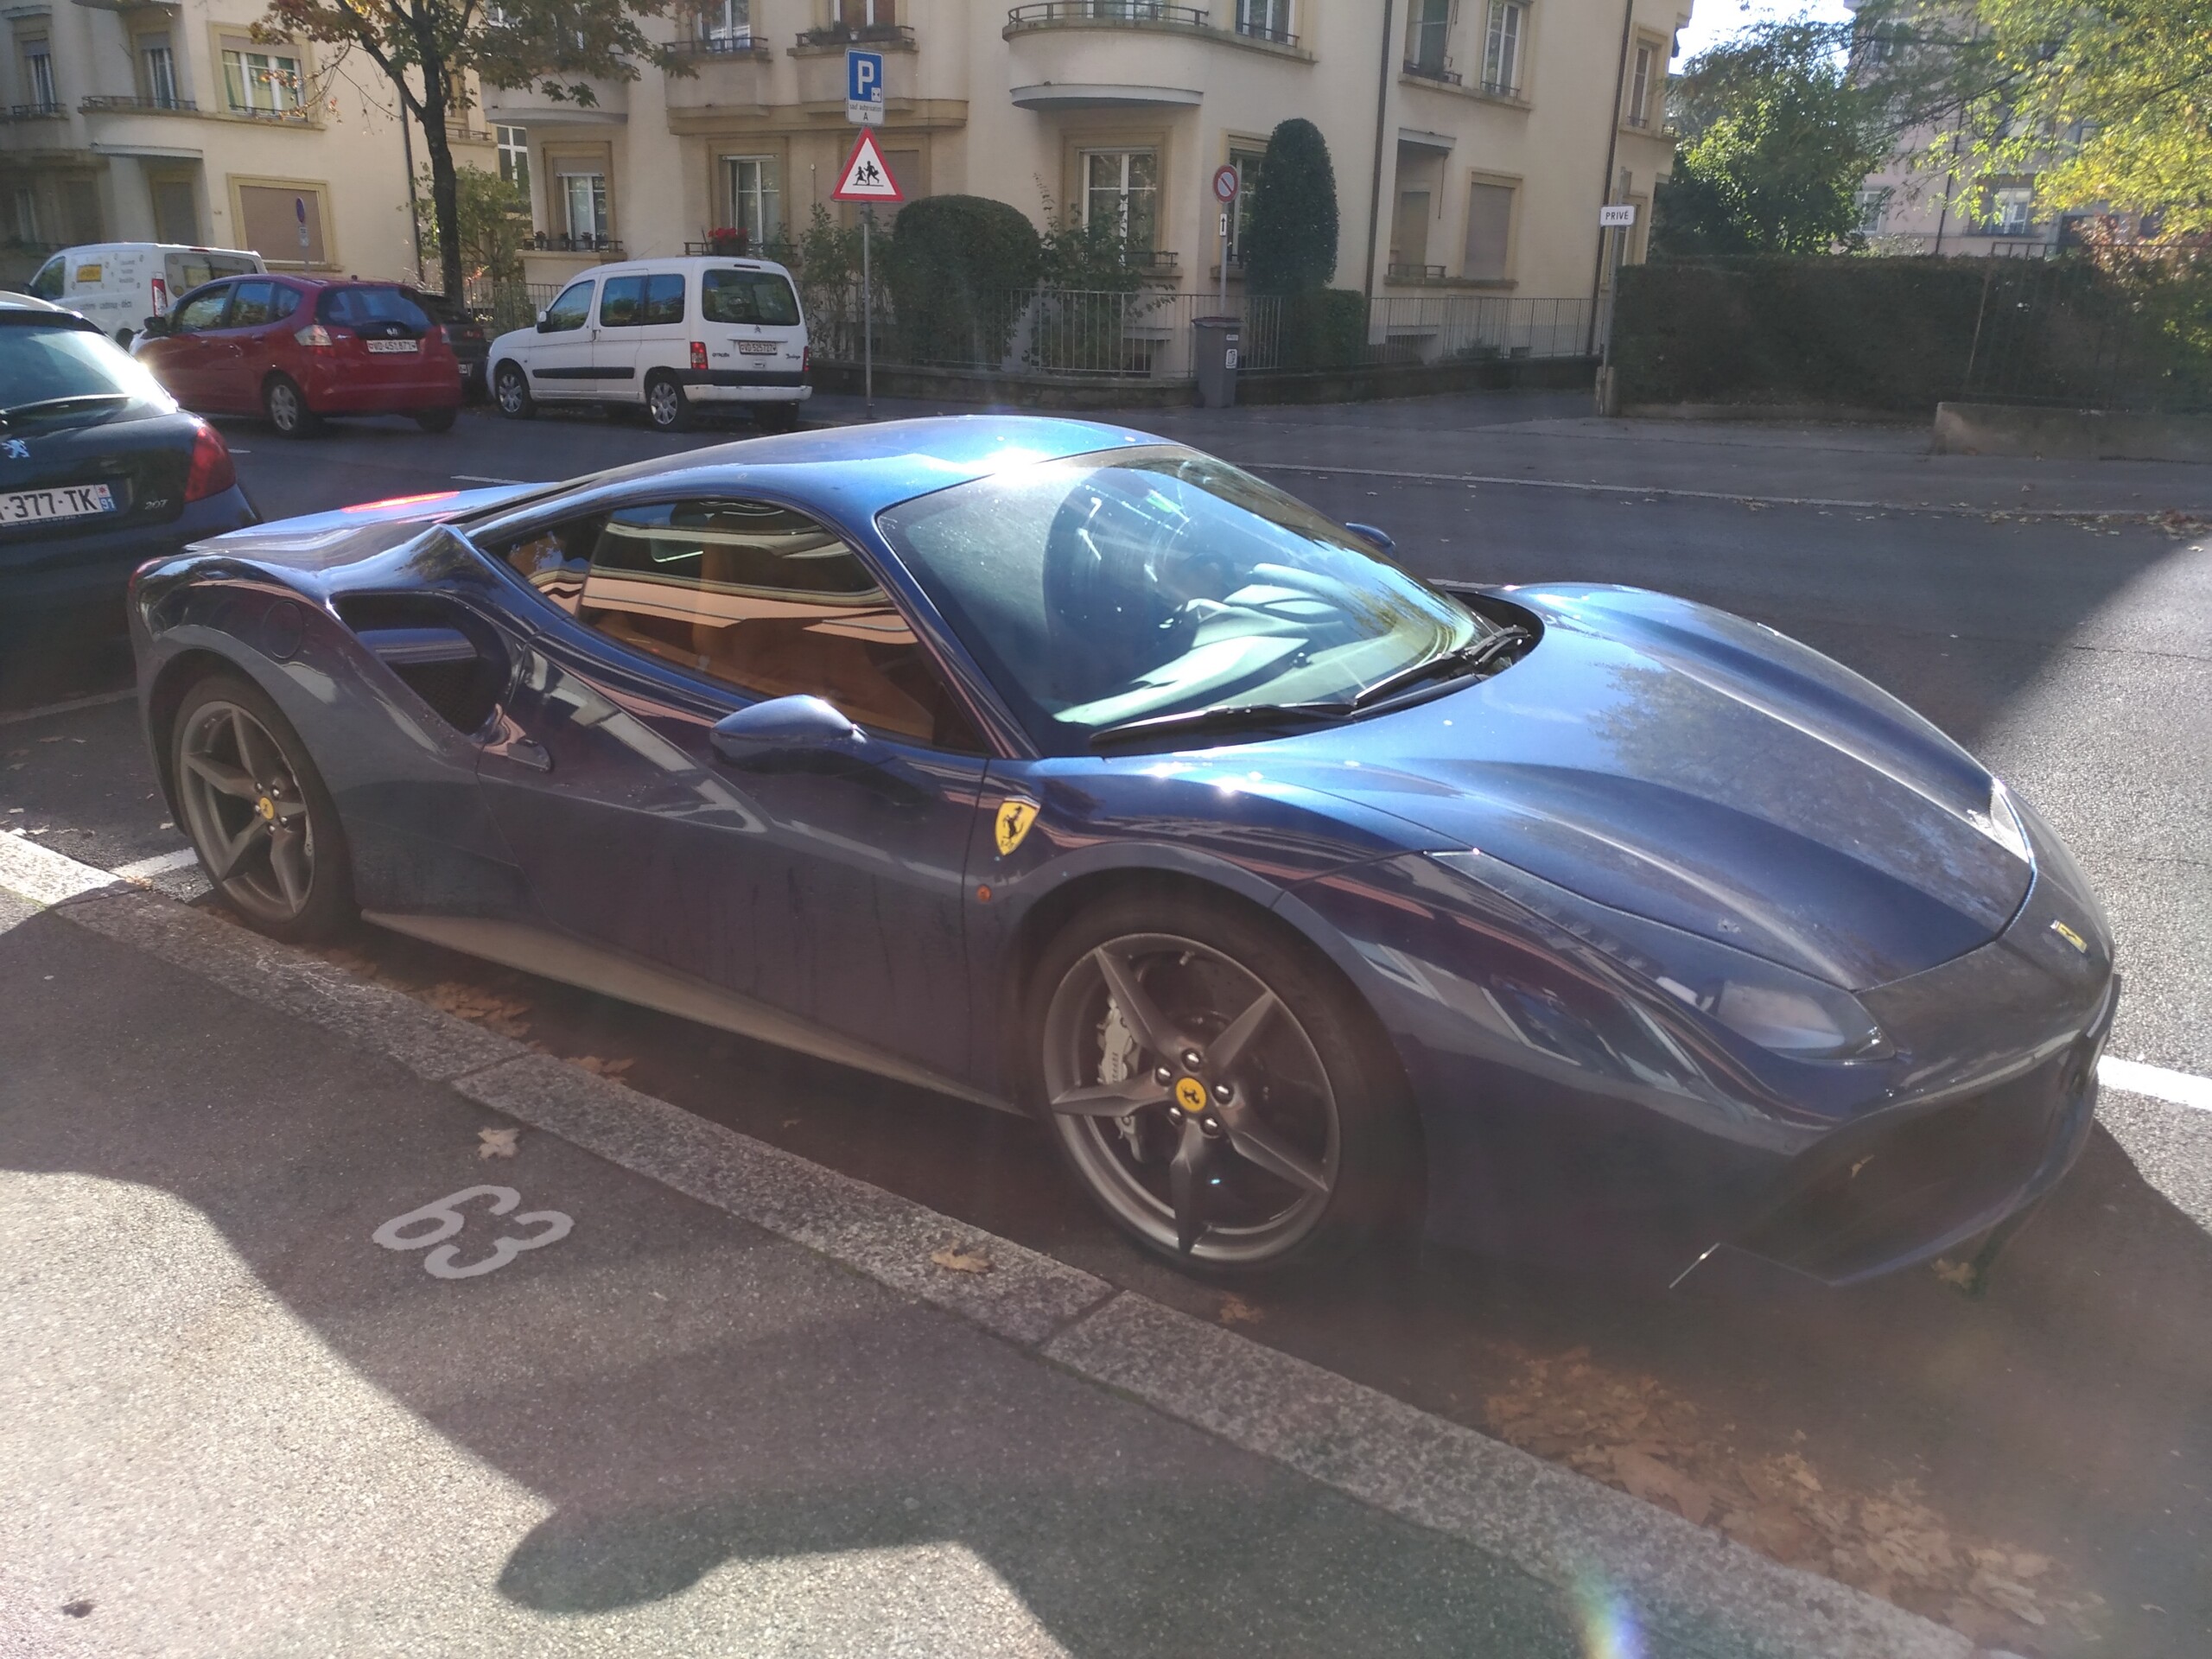
Ferrari could almost certainly sell more cars in the short term.
But maximum unit sales are not the objective.
The brand’s 2030 plan still refers to Enzo Ferrari’s principle of selling one car fewer than the market demands. That creates a useful challenge to one of the laziest assumptions in business: that an opportunity to sell more must automatically be taken.
Sometimes the refusal creates part of the value.
Scarcity is an extreme example, but the principle is broader.
More is not always better when the thing you are adding damages what made the original offer valuable.
Sometimes the Answer Is Not “No”. It Is “Not Under This Brand.”
This is where the subject overlaps with positioning and brand architecture — but it is worth keeping it within the strategy discussion because it shows another form of refusal.
A company can decide an opportunity is attractive while also deciding the existing brand should not be stretched to accommodate it.
Toyota and Lexus are probably the cleanest example.
In the 1980s, Toyota wanted to compete directly in the American luxury market against brands such as Mercedes-Benz and BMW. It did not simply put a much higher price on a Toyota and ask buyers to update everything they believed about the name.
It created Lexus.
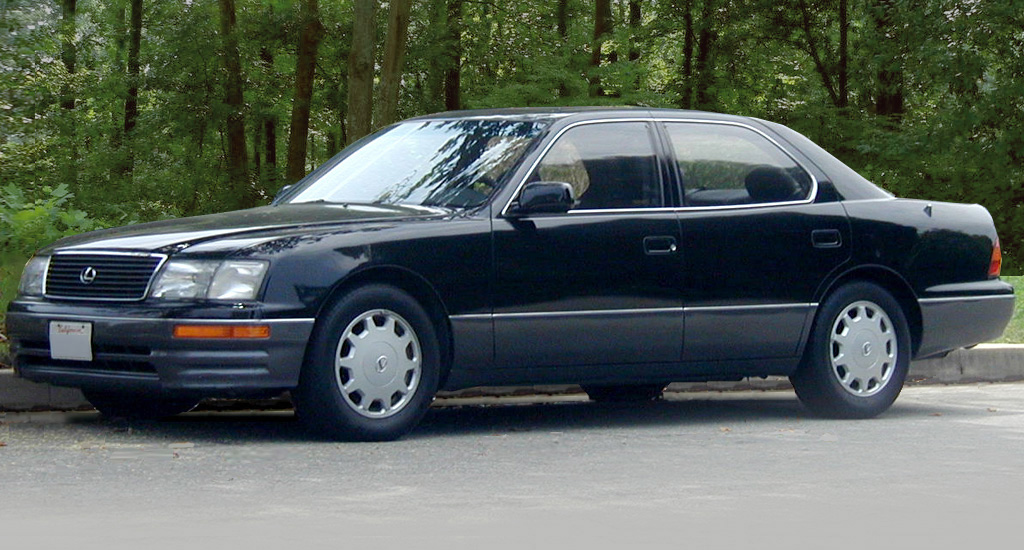
Toyota announced the separate Lexus luxury line in 1987 and launched it in the United States in 1989 with its own dealer network. Toyota’s own contemporary material described the LS 400 as a car designed to compete directly with leading European luxury marques.
The manufacturing capability could be shared.
The positioning did not have to be.
Honda had taken a similar route slightly earlier with Acura, launched in North America in 1986 as a separate luxury-performance brand. If Acura is unfamiliar in Britain, that is partly because it has historically been concentrated in North America. The important point is the same: Honda could pursue an upscale opportunity without making the Honda badge carry the whole strategic stretch.
A new brand is not always the answer — creating one is expensive and difficult.
But sometimes saying no to a brand extension is how a business says yes to growth.
Volkswagen Shows How Wide a Company Can Be Without Making One Brand Mean Everything
The Volkswagen Group takes this logic to a much larger scale.
The Group currently describes ten core brands organised across groups including Core, Progressive and Sport Luxury. Volkswagen, Škoda, SEAT/CUPRA, Audi, Bentley, Lamborghini and Porsche can benefit from group scale and shared capability while maintaining different positions.
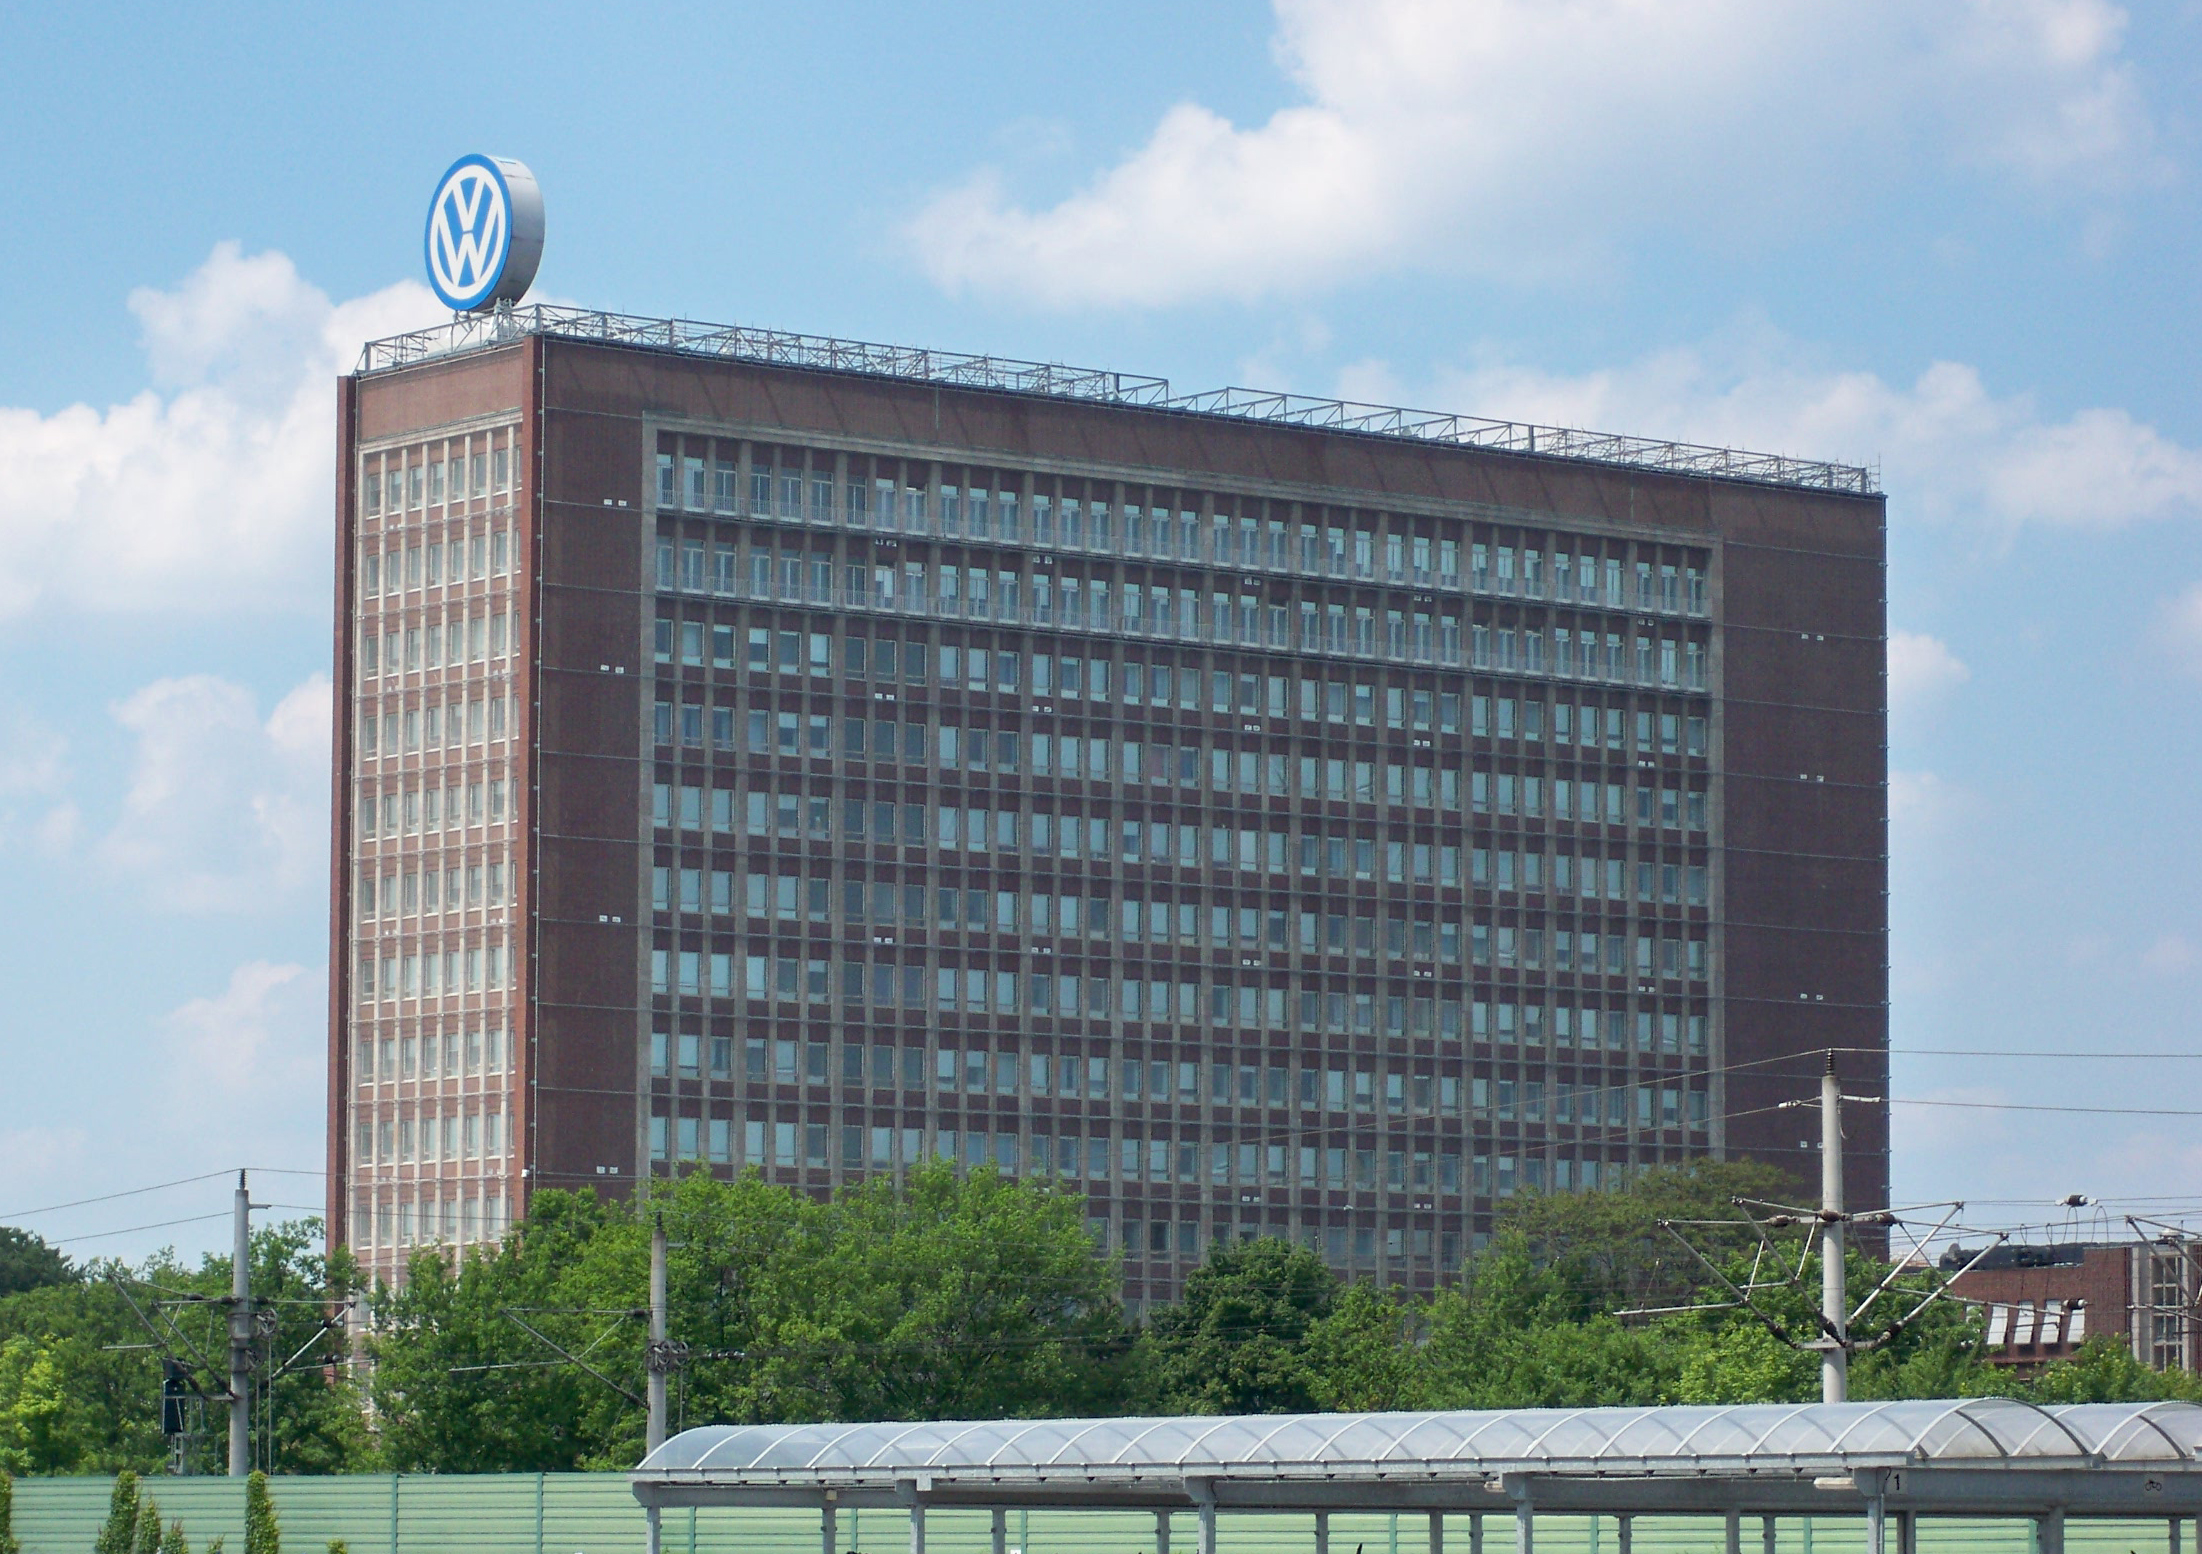
This matters because scale and focus are not opposites.
A corporation can be enormous while individual brands remain relatively specific.
The mistake would be assuming every capability must appear under the same customer-facing name.
A Bentley does not become more efficient because somebody writes Volkswagen across the bonnet.
Shared engineering, procurement, manufacturing or technology can sit behind distinct propositions.
That is a useful lesson for much smaller businesses too.
BMW Kept MINI Because MINI Meant Something BMW Did Not
BMW offers another version of the same idea.
When BMW sold most of the Rover Group in 2000, it retained MINI. The following year it relaunched the brand under BMW Group ownership.
BMW could build small cars. That was never really the strategic question.
The useful thing about MINI was that it already carried a completely different set of associations: compactness, British heritage, playfulness and distinctive design.
BMW Group could use its engineering and commercial capability without trying to make BMW itself mean exactly the same things.
That is one reason brand portfolios can create strategic freedom.
They let a business say: we want to serve that market, but we do not need this brand to serve it.
Marriott Does Not Ask One Hotel Brand to Serve Every Trip
Hotels make the point in a different way.
Marriott now operates more than 30 brands across luxury, premium, select, longer-stay and collection categories.
The Ritz-Carlton, Moxy, Courtyard, Residence Inn and St. Regis do not need to converge into one compromise hotel that sort of works for everybody.
The corporate business can chase enormous breadth.
The individual propositions can remain narrower.
This is useful because there is a temptation to think focus means a company must stay small.
It does not.
Focus can live at the level of the brand, the product, the audience or the operating model while the wider organisation expands through a portfolio.
P&G Is Huge — but You Do Not Buy “P&G Shampoo”
Procter & Gamble is another good illustration.
Its 2026 annual report describes a focused portfolio spanning categories such as fabric care, home care, baby care, grooming, hair care and personal health. Consumers encounter brands such as Ariel, Fairy, Pampers, Gillette, Oral-B and Head & Shoulders.
The corporation is broad.
The individual consumer propositions are much easier to understand.
This is not an argument that every company should create dozens of brands. Quite the opposite: brand proliferation creates its own complexity.
It is an argument that a company does not automatically have to force every commercial opportunity through the same brand identity.
Sometimes strategic focus means rejecting the opportunity. Sometimes it means rejecting the assumption that the opportunity belongs under your existing brand.
The important thing is preserving clarity about what each brand is for.
Trying to Serve Everyone Creates Real Operational Problems
I saw the opposite problem at Modal Electronics.
My view was that the business was trying to reach an extremely wide audience inside the synthesizer market: from very high-end flagship instruments to much more accessible products and different manufacturing propositions.
On paper, serving more segments increases the addressable market.
In reality, a smaller business does not have the resources of a global conglomerate.
Every segment needs product development, inventory, marketing, distribution and customer support. The proposition becomes harder to explain at exactly the same moment the organisation becomes harder to operate.
That is not a criticism of ambition.
It is a reminder that a strategy must fit the resources available to execute it.
A large company can sometimes operate several distinct businesses because it has the capital, teams and brand architecture to support them.
A smaller one can simply become spread thin.
Vanity Metrics Make Saying No Harder
Marketing has its own version of breadth addiction.
Reach is seductive.
A media opportunity that promises an enormous audience looks better on a slide than a small, specific audience. A social post with a million impressions looks more impressive than one that reaches 15,000 relevant people. A broad campaign creates bigger numbers even when the commercial effect is weak.
That encourages marketers to pursue opportunities because they are measurable rather than because they are useful.
The result can be a collection of flattering KPIs with very little strategic coherence.
The question should not be:
How many people could this reach?
It should be:
Which people do we need to reach, and what are we trying to make happen?
Why Saying No Feels So Difficult Inside a Business
There are several reasons.
The opportunity has a number attached
It is psychologically easier to defend potential revenue than the less visible value of staying focused.
Someone senior likes the idea
An initiative can survive because rejecting it feels like rejecting the person who proposed it.
Competitors are doing it
Activity elsewhere can turn an optional channel or product into something that suddenly feels mandatory.
New things are more interesting
Launching is emotionally more rewarding than improving something that already exists.
Breadth creates big-looking numbers
Reach and audience size can disguise weak fit with the customers who actually matter.
We assume complexity will be manageable
The downside often appears later, after the product, channel or partnership has become somebody’s responsibility.
All of those pressures make a clear strategy valuable.
If the organisation has already decided who it serves, what it believes, how it competes and what it refuses to become, individual decisions get easier.
The strategy has done some of the saying no in advance.
The Strategic No Test
Before adding a product, channel, audience or partnership, I would ask five questions.
Does this make what we stand for clearer or blurrier?
If the opportunity forces the brand to contradict itself, the revenue may not be worth the dilution.
Does it serve the audience we actually chose?
An enormous audience is not automatically a relevant audience.
What complexity arrives with the opportunity?
Count the SKUs, changeovers, stock, support, systems and management time — not only the top-line sales.
What gets less attention if we say yes?
Every initiative consumes something that could have strengthened the core.
If the market is attractive, does it belong under this brand?
Sometimes the right answer is a separate proposition rather than stretching the existing one.
Focus Is Not the Same as Rigidity
There is an obvious danger in taking this argument too far.
Businesses that never change eventually become case studies for somebody else’s disruption article.
A strategy cannot become an excuse for ignoring evidence.
Ferrari is introducing electric cars. Ryanair keeps changing elements of its customer experience. Aldi develops its range. BMW has evolved MINI repeatedly. Toyota did not stay out of luxury because Toyota had historically been associated with mainstream cars.
The distinction is between evolution that reinforces the proposition and expansion that makes the proposition incoherent.
A useful strategy does not make every answer “no”.
It gives the business a reason for its yeses.
The Best Strategy May Look Smaller on a Slide
A focused strategy can look unimpressive in a brainstorm.
Fewer audiences.
Fewer products.
Fewer channels.
Fewer initiatives.
Fewer exciting logos on the partnership page.
But the remaining choices can reinforce one another.
That is the bit a slide full of opportunities does not show.
At Paleo Ridge, refusing to sell food that contradicts the belief in raw feeding protects the message.
At Ferrari, controlled volume protects exclusivity.
At Ryanair, rejecting full-service complexity protects the low-fares model.
Toyota could pursue luxury without requiring Toyota itself to mean luxury.
Volkswagen Group, Marriott and P&G demonstrate that a corporation can grow extremely broad while individual brands retain clearer jobs.
The common thread is not smallness.
It is choice.
Good strategy does not eliminate opportunity. It stops opportunity from eliminating focus.
Sources and Further Reading
- Harvard Business Review — Michael Porter, “What Is Strategy?”
- Harvard Business School Institute for Strategy and Competitiveness — Strategy Explained
- Ryanair — 2026 Annual Report
- Aldi UK — About Aldi
- Ferrari — 2025 Annual Report
- Ferrari — 2030 Strategic Plan
- Toyota — announcement of the Lexus luxury brand, 1987
- Toyota — Lexus production begins, 1989
- Honda — history of the Acura brand
- Volkswagen Group — Brands and Brand Groups
- BMW Group — history of BMW, MINI and Rolls-Royce
- Marriott — brand portfolio
- P&G — 2026 focused brand portfolio
- Wikimedia Commons — Ferrari 488, Guillaume Vachey, CC0
- Wikimedia Commons — Lexus LS 400, public domain
- Wikimedia Commons — Volkswagen Group headquarters, Vanellus Foto, CC BY-SA 3.0